Disability Insurance Deep Dive – Post 7 – Income Protection for Residents And New Attendings
For a resident or new attending, the most valuable asset isn’t a house or a portfolio it’s the future earning power that years of education have been building toward. A single disabling illness or injury during or after training can erase millions in lifetime income. Yet residency is also the moment when protecting that asset…
Disability Insurance Deep Dive – Post 6 – Executive Carve Out Guaranteed Issue Income Protection
Earlier in this series we established the core problem for high earners: group long-term disability (LTD) caps benefits at a level that protects a shrinking share of income as pay rises. Combine that with the fact that buying an individual policy the traditional way means clearing rigorous medical underwriting where a meaningful share of applicants…
Disability Insurance Deep Dive – Post 5 – Protecting the Business When an Owner or Key Person Is Disabled
Most disability planning focuses on the individual: replacing a paycheck when illness or injury stops it. But for business owners, and for companies that depend on a few essential people, a disability creates a second, separate problem. The bills don’t stop, the revenue that one person generated disappears, and an ownership stake can suddenly need…
Disability Insurance Deep Dive – Post 4 – High-Limit Disability Insurance for $500K+ Earners
Earlier posts in this series traced how a group long-term disability (LTD) plan quietly under-protects high earners, and how an individually owned policy rebuilds much of that gap. But there’s a ceiling to what the traditional market will do. Once your income climbs past roughly half a million dollars, even group LTD stacked with a…
Disability Insurance Deep Dive – Post 3 – Individual Disability Riders: When to Add
In the previous posts we established why high earners need individual disability insurance (IDI) layered on top of their group plan. But a base IDI policy is only the starting chassis. What actually determines how and whether the policy pays when life gets complicated is the set of riders you attach to it. Riders are optional…
Disability Insurance Deep Dive – Post 2 – The Group LTD Gap and How to Close
In the first post of this series, we mapped the layers of income protection and noted a quiet problem: the higher your income, the smaller the share of it your group long-term disability (LTD) plan actually protects. This post takes that problem apart piece by piece explaining where the gap comes from, how large it…
Disability Insurance Deep Dive – Post 1 – Income Protection Types
The Building Blocks of Income Protection Most people insure the things their income pays for; the house, the cars, their health while leaving the income itself uninsured. Yet your ability to earn a paycheck is very likely the most valuable asset you own. A 40-year-old earning $200,000 who works another 25 years will earn $5…
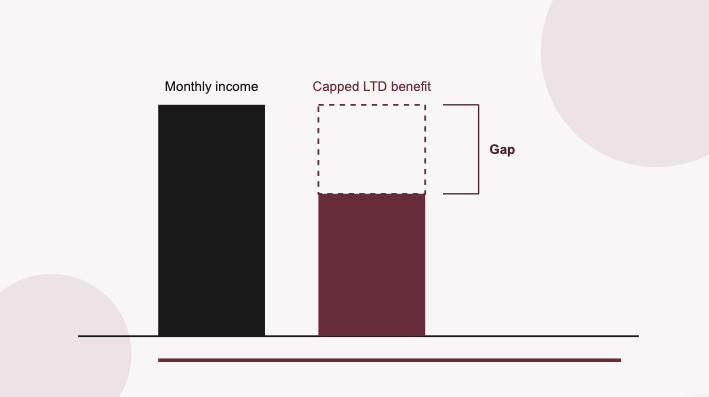
The income protection gap: what physicians often miss about group disability coverage
STRATEGIC EXECUTIVE BENEFIT PLANS • • Educational – not a solicitation for a specific policy Original illustration by Professional Benefits Incorporated. A group long-term disability benefit is often capped well below full income, leaving a monthly gap. Why can group LTD leave physicians underinsured? Group long-term disability insurance can leave physicians underinsured because benefits are…